

SAP Business One for Pharma: Uncovering Hidden Product-Line Profitability Gaps
Quick Answer
SAP Business One for Pharma helps pharmaceutical manufacturers identify hidden profitability gaps by connecting purchasing, inventory, production, sales and financial transactions. With appropriate costing methods and reporting configurations, businesses can analyse raw material consumption, production expenses, distributor discounts and product-wise gross margins to make more informed pricing, manufacturing and portfolio decisions.
The Financial Blind Spot Behind Growing Pharmaceutical Sales
Increasing pharmaceutical sales does not always translate into increasing profitability.
A manufacturer may experience strong demand for tablets, capsules, syrups or injectable medicines while generating progressively lower margins. Rising ingredient prices, production inefficiencies and commercial discounts can gradually weaken the financial contribution of even the best-selling products.
The challenge is that traditional financial reports often focus on overall revenue, operating expenses and business-wide profits. Although these indicators explain general financial performance, they may not reveal which formulations are genuinely profitable.
Consider two pharmaceutical products:
- A high-volume formulation generating substantial revenue but carrying expensive raw materials and significant distributor discounts.
- A lower-volume formulation generating less revenue but maintaining stronger margins through efficient production and favourable commercial terms.
Without detailed product-wise profitability analysis, management may continue investing in the first product while overlooking the financial potential of the second.
This disconnect creates a significant business risk. Pricing revisions, manufacturing investments and product portfolio expansion may be based on revenue assumptions rather than actual financial contribution.
For pharmaceutical CEOs and CFOs, understanding the relationship between product costs and realised revenue is essential to protecting sustainable growth.
The Hidden Costs Eroding Pharmaceutical Product Margins

Hidden cost drivers in pharmaceutical manufacturing: Tracking raw material variances, batch yields, packaging, and indirect overheads in SAP Business One.
Pharmaceutical manufacturing involves multiple cost components that extend beyond the purchase price of raw materials. Expenses accumulate throughout formulation, processing, quality-related activities, packaging and distribution.
When these costs are not captured or allocated appropriately, product margins may appear healthier than they actually are.
Raw Material Price Fluctuations
Active pharmaceutical ingredients (APIs), excipients, solvents and specialised materials directly influence formulation costs.
Changes in supplier pricing, import expenses and exchange rates can increase procurement costs. However, outdated costing assumptions may prevent finance teams from recognising the impact on individual products.
A formulation that was profitable six months ago may no longer deliver the expected margin at its existing selling price.
Production Yield and Material Consumption Variances
Actual material consumption may differ from planned Bill of Materials (BOM) quantities because of production losses, process variations, adjustments or rejected output.
When fewer saleable units are produced from the same quantity of raw materials, the manufacturing cost per acceptable unit can increase.
Without reviewing production consumption and yield variances, management may underestimate the cost of manufacturing particular formulations.
Manufacturing Overhead Allocation
Production facilities incur indirect expenses related to labour, equipment, utilities, maintenance and facility operations.
Different pharmaceutical products may consume these resources at different rates. Allocating expenses using a single broad average can distort product-level cost estimates.
An appropriate overhead allocation method helps finance teams evaluate whether reported manufacturing costs reflect the resources consumed by each product.
Packaging and Quality-Related Expenses
Packaging requirements vary across pharmaceutical products. Blister packs, bottles, vials, specialised cartons and protective materials contribute differently to manufacturing expenses.
Testing, inspection and quality-related activities may also influence product economics. Their financial treatment should reflect the company’s accounting policies.
These expenses need to be considered when determining the relevant cost of manufacturing and supplying each product.
Expired Inventory and Product Returns
Expired stock, damaged inventory and customer returns can affect the financial performance of pharmaceutical product lines.
Where write-offs and returns are not associated with the relevant products, management may struggle to determine which formulations are generating additional financial losses.
Depending on the reporting objective, these expenses may need to be analysed separately from standard gross margin calculations.
Revenue Leakage Across Pharmaceutical Distribution Channels
Manufacturing cost represents only one side of profitability. Pharmaceutical companies must also understand the revenue recognised after applicable commercial adjustments.
Distributor discounts, volume-based pricing, promotional incentives, sales returns and credit adjustments can reduce product revenue.
The same pharmaceutical formulation may therefore generate different margins across customers and distribution channels, even when its manufacturing cost remains similar.
| Commercial factor | Potential impact on profitability |
|---|---|
| Distributor discounts | Lower net selling prices |
| Promotional incentives | Reduced revenue or higher selling expenses |
| Customer-specific pricing | Margin differences across customers |
| Sales returns and credit notes | Revenue reversals and related cost adjustments |
| Expired stock claims | Additional losses or commercial adjustments |
| Volume-based agreements | Reduced margins despite higher sales quantities |
The accounting treatment of these adjustments must be consistent. Some incentives may reduce recognised revenue, while others may represent selling expenses, depending on the arrangement and applicable accounting policies.
A product’s invoiced sales value should not be treated as its final financial contribution without considering these factors.
Product-Wise Profitability Analysis Beyond Sales Revenue
Product profitability analysis helps pharmaceutical companies understand the financial performance of individual formulations, product categories and distribution channels.
Three important financial measures support this evaluation.
Gross Profit
Gross profit represents the difference between net sales revenue and the applicable cost of goods sold (COGS).
Gross Margin
Gross margin expresses gross profit as a percentage of net sales revenue.
Contribution Margin
Contribution margin measures the revenue remaining after relevant variable costs are deducted.
It helps management evaluate how much a product contributes towards covering fixed costs and generating operating profit.
Gross margin and contribution margin should not be used interchangeably. A product may report a favourable gross margin but generate a lower contribution after variable distribution and selling expenses are considered.
Additional expense allocations may be required to estimate overall product-level operating profitability.
Illustrative Pharmaceutical Product Profitability Comparison
Consider a pharmaceutical manufacturer evaluating two product lines over the same reporting period.
| Financial indicator | Product A | Product B |
|---|---|---|
| Gross sales | ₹50,00,000 | ₹35,00,000 |
| Sales discounts and adjustments | ₹5,00,000 | ₹2,00,000 |
| Net sales revenue | ₹45,00,000 | ₹33,00,000 |
| Cost of goods sold | ₹38,00,000 | ₹23,00,000 |
| Gross profit | ₹7,00,000 | ₹10,00,000 |
| Gross margin | 15.56% | 30.30% |
Illustrative example for explanation purposes; not actual customer results.
Although Product A generates higher sales revenue, Product B delivers greater gross profit and a significantly stronger gross margin.
This comparison demonstrates why pharmaceutical manufacturers should evaluate profitability alongside sales performance rather than using revenue alone to determine product priorities.
Business Decisions at Risk Without Reliable Profitability Data
Incomplete product costing and revenue information can affect several strategic decisions.
- Product portfolio planning: Management may prioritise high-volume formulations while overlooking products that generate stronger financial returns.
- Pricing strategy: Selling prices may remain unchanged even after raw material expenses and manufacturing costs increase.
- Production capacity allocation: Equipment, labour and materials may be committed to products without sufficient visibility into their financial contribution.
- Procurement planning: Supplier negotiations may focus on purchase prices without evaluating their broader impact on finished product costs.
- Financial forecasting: Revenue projections may appear favourable while expected margins decline because of changing production expenses and commercial arrangements.
These challenges become increasingly important as pharmaceutical companies expand manufacturing capacity, introduce new formulations or enter additional distribution markets.
A reliable profitability model provides management with a consistent financial basis for making these decisions.
SAP Business One for Pharma as an Integrated Costing and Financial Management Platform
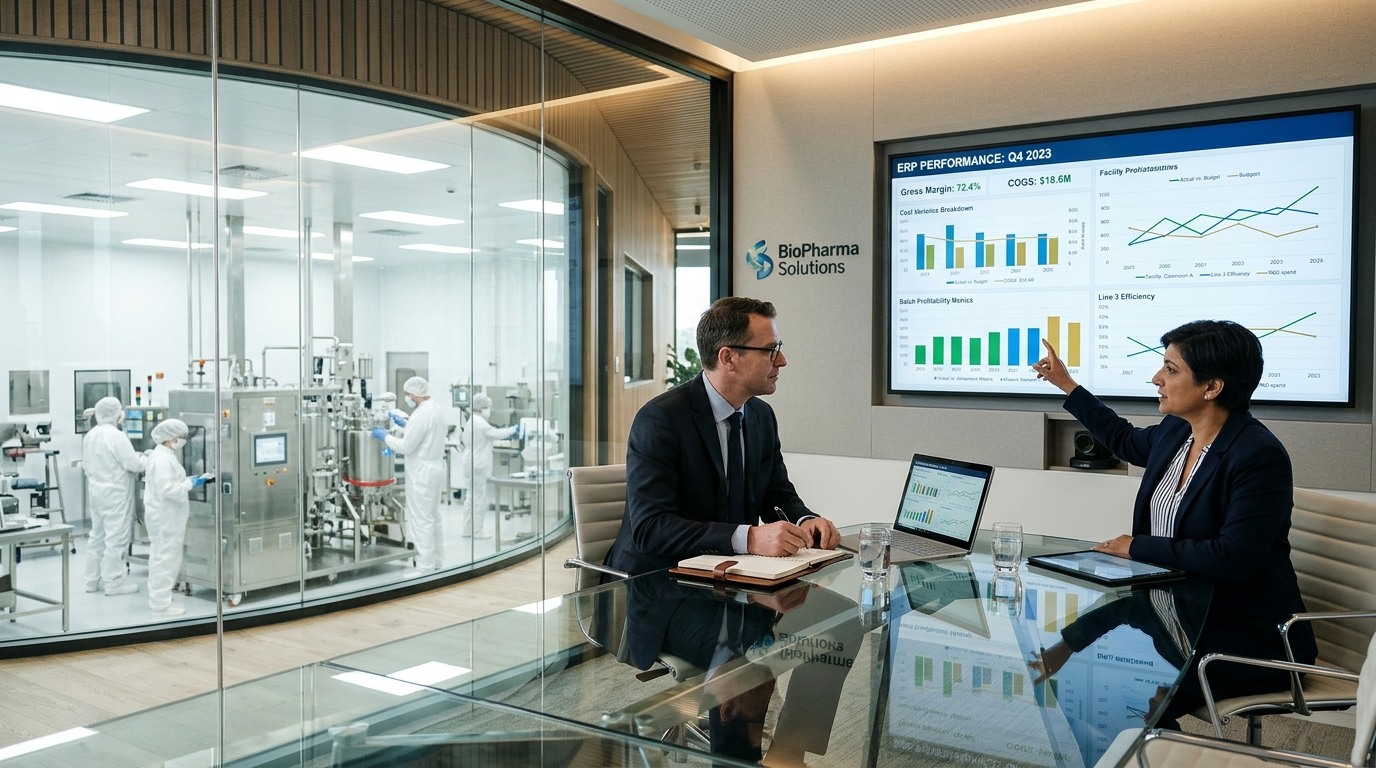
Integrated pharma ERP costing: Connecting procurement records, BOMs, inventory valuation, and sales data in SAP Business One.
SAP Business One connects essential business functions within an integrated ERP environment, helping pharmaceutical manufacturers establish a consistent foundation for product cost and profitability analysis.
Rather than relying entirely on disconnected spreadsheets, finance teams can evaluate information from purchasing, inventory, production and sales transactions.
Procurement and Material Cost Visibility
Purchasing records help businesses review supplier prices, purchase quantities and material procurement expenses.
Inventory information provides visibility into stock movements and valuation. Relevant landed cost transactions can also help account for applicable additional procurement expenses.
Together, these records support a more informed assessment of material cost changes and their impact on product margins.
Bill of Materials and Production Costing
The Bill of Materials defines the components and quantities required to manufacture a product.
Production orders, material issues and finished goods receipts help establish the relationship between planned manufacturing requirements and recorded production activities.
SAP Business One also supports production order cost information and variance analysis. This can help manufacturers identify differences between expected production requirements and recorded component costs.
Reliable analysis depends on accurate BOM structures, complete production transactions and appropriate system configuration.
Inventory Valuation and Batch Costing
Inventory valuation methods influence how material and finished goods costs are recorded.
Depending on the business requirements and item configuration, SAP Business One supports valuation approaches such as standard cost, moving average, FIFO and serial/batch valuation.
For pharmaceutical manufacturers, it is important to distinguish batch traceability from batch-specific financial valuation. Tracking a batch number does not automatically mean the system calculates a separate inventory cost for that batch.
Where applicable, serial/batch valuation and relevant production cost recalculation capabilities can support more detailed batch-related cost analysis.
Manufacturing Resource and Overhead Management
Resource-related production costs and additional component expenses can contribute to manufacturing cost evaluation.
However, indirect manufacturing expenses may require defined allocation rules, cost accounting structures or additional reporting.
The costing model must reflect the organisation’s accounting policies and the operational complexity of its pharmaceutical manufacturing processes.
Sales and Financial Integration
Sales transactions provide information about product quantities, pricing, discounts, customer activity and revenue adjustments.
When evaluated alongside relevant COGS and financial records, this information supports product-wise gross margin analysis.
Specific distributor incentive structures, indirect cost allocations or detailed profitability requirements may require configured reports, custom dashboards or integrations.
A Connected Framework for Pharmaceutical Profitability Management
An effective pharmaceutical ERP reporting model connects the financial impact of each major business activity.
| Business function | Information captured | Management insight |
|---|---|---|
| Purchasing | Material prices and procurement expenses | Supplier cost impact |
| Inventory | Stock quantities and valuation | Material and finished goods costs |
| Production | Consumption, resources and variances | Manufacturing cost performance |
| Sales | Revenue, prices and discounts | Commercial performance |
| Finance | COGS and relevant expense allocations | Product profitability |
| Management reporting | Consolidated financial indicators | Pricing and portfolio decisions |
The objective is to establish a reporting model in which each relevant transaction contributes to a consistent understanding of product performance.
Integration reduces the need for repeated manual consolidation, but accurate results still depend on data quality, transaction discipline and properly defined financial calculations.
For more information about industry-specific ERP capabilities, explore SAP Business One for the Pharmaceutical Industry.
Financial Indicators That Pharma CEOs and CFOs Should Monitor
Pharmaceutical management dashboards should provide more than total sales and overall profit figures. They should highlight the underlying factors influencing product-line performance.
| Financial KPI | Management purpose |
|---|---|
| Gross margin by product | Identify declining or low-margin formulations |
| Net revenue by product | Evaluate revenue after applicable adjustments |
| Manufacturing cost per unit | Understand production cost changes |
| Material cost variance | Monitor differences in procurement and material usage costs |
| Production yield variance | Identify deviations from expected output |
| Discount percentage | Evaluate the financial impact of commercial terms |
| Inventory write-off value | Monitor losses associated with expired or damaged stock |
| Contribution margin | Assess product contribution after variable expenses |
| Gross margin trend | Identify profitability changes across reporting periods |
Reviewing these indicators collectively helps management determine whether margin deterioration originates from procurement, manufacturing or commercial activities.
A CFO may use the information to evaluate pricing revisions, while an operations head may investigate material consumption or production efficiency.
Dashboards should also identify the calculation basis, reporting period and source transactions behind each KPI.
This ensures that management decisions are based on meaningful financial information rather than isolated performance indicators.
A Practical Roadmap for Closing Product-Line Profitability Gaps
Implementing or optimising SAP Business One for Pharma requires more than enabling financial reports. Pharmaceutical companies should establish a structured approach to improving the accuracy of product cost and revenue information.
Step 1: Evaluate Existing Profitability Reporting
Identify how the organisation currently calculates product costs, gross margins and commercial adjustments.
Determine which data is maintained outside the ERP system and where manual reconciliation is required.
Step 2: Standardise Product and Material Master Data
Review finished goods, raw materials, packaging items, units of measurement and product classifications.
Consistent master data establishes the foundation for reliable costing and product-category comparisons.
Step 3: Validate BOMs and Inventory Valuation
Confirm that BOM quantities reflect applicable manufacturing requirements.
Review inventory valuation methods, production cost calculation rules and the treatment of material consumption.
Step 4: Define Manufacturing Cost Allocation
Identify relevant direct and indirect manufacturing expenses.
Establish appropriate resource rates and overhead allocation rules based on the organisation’s financial policies.
Step 5: Align Revenue and Discount Reporting
Review customer pricing, distributor agreements, sales returns, credit notes and applicable commercial incentives.
Ensure that product profitability reports reflect the correct net revenue calculation without double-counting adjustments.
Step 6: Build Product-Level Profitability Reports
Develop reports that compare revenue, COGS, gross profit, gross margin and relevant additional costs.
Where necessary, evaluate custom reporting, dashboards or integrations to address industry-specific requirements.
Step 7: Establish Continuous Margin Reviews
Create a regular financial review process involving finance, procurement, production and commercial teams.
Reconcile profitability reports with financial records and investigate material differences before making pricing or portfolio decisions.
This approach is relevant to both new ERP implementations and pharmaceutical companies already using SAP Business One.
Emerging Alliance’s Approach to Pharmaceutical Profitability Visibility
Pharmaceutical businesses require an ERP implementation approach that considers manufacturing complexity alongside financial management requirements.
Emerging Alliance helps organisations evaluate SAP Business One capabilities, business processes, system configurations and reporting requirements to address operational and financial visibility gaps.
For pharmaceutical manufacturers, this can include:
- Product costing and inventory valuation assessment.
- BOM and production process evaluation.
- Financial reporting and cost allocation configuration.
- Distributor pricing and discount analysis.
- Custom profitability reports and management dashboards.
- Integration with relevant business applications.
- SAP Business One implementation, optimisation and ongoing support.
For existing SAP Business One users, an assessment can help determine whether profitability gaps arise from incomplete transactions, unsuitable configurations, inconsistent costing methods or reporting limitations.
A complete ERP replacement may not be necessary when the underlying system can support the required business processes through appropriate improvements.
From Revenue-Driven Growth to Profitability-Driven Decisions
Pharmaceutical growth becomes more sustainable when management understands not only how much each product sells, but also how much financial value it generates.
Rising material costs, production variances, packaging expenses and distributor discounts can gradually weaken the profitability of otherwise successful formulations.
SAP Business One provides an integrated foundation for connecting these activities with financial reporting. With reliable data, appropriate configuration and industry-specific reporting, manufacturers can improve their understanding of product margins and make better-informed decisions.
For business leaders, the priority is to build a financial management environment where pricing, procurement, production and portfolio strategies are guided by measurable product performance.
Frequently Asked Questions
Discover What Drives Your Pharma Product Profitability
Gain better visibility into product costs, distributor pricing, and profit margins with SAP Business One.
Request a SAP Business One for Pharma Demo with Emerging Alliance to identify hidden profitability gaps and improve financial decision-making.